In an era of total measurability, financial services often become a mere exchangeable commodity.
However, the creation and preservation of substantial values follow a different logic. Here, value is not a mere calculated figure; rather, it is an expression of an attitude of trust and empowerment. At Westend Bank, we therefore view banking as bespoke craftsmanship that provides the resilient structural framework—the "stability"—for our clients' visions.
Our model of fronting is defined by this self-image. It leaves behind the well-trodden paths of standard banking because we are not interested in off-the-shelf capital. We provide our regulatory infrastructure as a discreet, high-precision foundation to make individual financial concepts feasible in the first place. It is the subtle but decisive difference between a functional utility building and an excellently planned gallery: both offer space—but only the gallery creates the frame that the art (in our case, your vision) demands.
How Fronting & Credit Mandates Differ.
Where non-banks face regulatory limits, we enable structures within legal and supervisory requirements. We do not view a fronting loan at Westend Bank as a purely regulatory service, but as the provision of a high-load infrastructure. As an institutional bridge, we translate individual financing visions into a legally secure framework, differentiating precisely according to the objectives of the mandate.
The Credit Mandate: Continuity in One Hand
With a Credit Mandate (Kreditauftrag), the entire credit management remains in-house even after disbursement. This guarantees the highest level of administrative security and seamless support throughout the entire term. It is the ideal solution for partners who value a comprehensive, one-stop service.
Fronting: Credit Ownership for Investors
In the area of Loan Fronting, we focus on the functions that strictly require the privilege of a banking license. Our role: we conduct the creditworthiness assessment and ensure the regulatory framework. Following disbursement, the credit relationship is transferred to the investor via a sale.
This approach separates regulatory necessity from economic ownership. It allows third parties to fully assume and manage the opportunities and risks arising from the credit relationship.
"True value cannot be expressed in numbers alone; it is not a matter of having, but of being."
Why is a Bank Needed for Fronting?
The necessity of a fronting bank is the direct result of a sophisticated regulatory landscape designed to protect trust in our financial order. Anyone establishing commercial credit structures in Germany operates within the framework of the German Banking Act (KWG)—a set of rules that places the highest demands on all participants.
Many institutions, family offices, and specialized funds possess outstanding market expertise and the necessary liquidity, yet operate without their own banking license. In this field of tension, Westend Bank acts as a strategic enabler.
Transformation into Bank-Compliant Substance
We translate your financing vision into a high-precision, bank-compliant financing solution. In doing so, we ensure that all processes—from identification (KYC) and strict adherence to Anti-Money Laundering (AML) standards to debt service capability—do not merely meet the expectations of BaFin and the Minimum Requirements for Risk Management (MaRisk) but are understood as a hallmark of quality.
We do not view this deep audit as a bureaucratic hurdle, but as a shield: it secures not only the integrity of the system and our clients' investments but, above all, protects their most valuable asset—their reputation.
True solutions arise from dialogue. Let us examine the structural integrity of your vision together.
What Does Fronting Mean in the Insurance Industry?
The origin of fronting lies in the world of insurance—an industry traditionally shaped by the balance between risk and market access. In that context, the model serves to underwrite policies in territories where an institution does not hold a local license. An established primary insurer acts externally as the fronting provider, while the economic risk is carried in the background.
Differentiation: Market Access vs. Risk Diversification
It is essential to precisely distinguish fronting from classic reinsurance:
- Reinsurance: A tool for internal balance sheet relief and risk diversification between insurers.
- Fronting: A strategic tool for obtaining market access. Here, the partner primarily provides its regulatory "face" and its infrastructure.
Our Philosophy: Beyond Banking
In our understanding of "Beyond Banking," we transfer this logic of empowerment to the credit market. We utilize the proven stability of supervisory safeguarding to pave the way for sophisticated actors to access new financing spaces. In this process, Westend Bank acts as a guarantor for the stability-oriented and regulatory integrity of the entire construct.
Overview: Fronting in Banking vs. Insurance
| Feature | Fronting in Banking | Fronting in Insurance |
|---|---|---|
| Primary Purpose | Regulatory Enablement (KWG) | Global Market Access & Risk Transfer |
| Role of Institution | Strategic Licensor | Local Risk Bearer (Fronting Provider) |
| Strategic Focus | Capital Allocation & Structuring | Hedging & Reinsurance |
| Core Value | Bespoke Financial Visions | Risk Management & Coverage |
Which Legal Aspects Must Be Observed in Fronting?
The legal architecture of a fronting agreement is a work of supreme regulatory precision and rests on the following pillars:
1. Supervisory Compliance & Adherence to MaRisk
Every structure must withstand the Minimum Requirements for Risk Management (MaRisk). We guarantee proper credit voting and seamless risk assessment that meets the strict audit standards of the supervisory authorities at all times.
2. KWG Licensing Requirements
We ensure that lending complies with the legal norms of the German Banking Act (KWG) at every stage. This consistently eliminates regulatory risks for our partners and creates a legally secure space for their ambitions.
What are the Advantages of a Fronting Agreement for Family Offices and Companies?
The primary advantage of a fronting agreement lies in immediate operational capability. It opens access for companies to business opportunities that require a highly specialized banking supervisory infrastructure, without them having to bear the administrative complexity and regulatory burden of their own institution.
Our clients benefit from a significant increase in operational efficiency: while they focus entirely on the selection and strategy of their assets, we handle the banking architecture, settlement, and seamless compliance.
Discretion and Structural Stability
Furthermore, this model offers the highest degree of discretion. As an experienced partner in the background, we guarantee the regulatory safeguarding that allows our clients' financing concepts to be implemented with precision and legal certainty. A symbiosis arises that is rare in the modern financial world: entrepreneurial agility meets banking stability.
Are There Risks or Disadvantages to Fronting?
Where spaces for innovation are created, potential risks must be viewed with analytical sharpness. For us, transparency is not a regulatory evil, but the prerequisite for a sustainable Architecture of Trust. Once the bank has fulfilled the required due diligence in the lending process, the client assumes the opportunities and risks arising from the credit relationship.
Fronting in Practice: Westend Bank Use Case
Optimizing Project Finance
Initial Situation: Dynamism Meets Static Structures
An entrepreneurially active group was developing a modern residential quarter—a project with approximately 500 units across 35,000 square meters. As the project progressed, a financing agreement due for extension needed to be replaced. The goal: to replace the existing structure with a model that better suited the increased complexity and the need for entrepreneurial freedom.
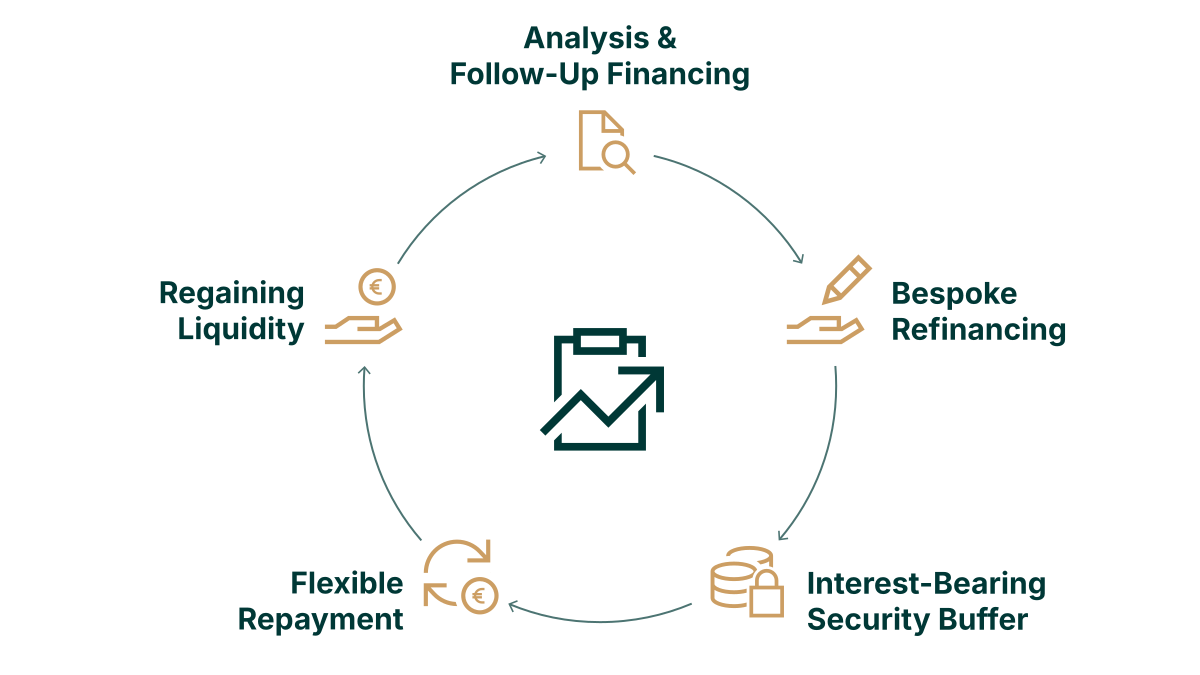
The Solution: The Bespoke Credit Mandate
In close coordination with the client, Westend Bank granted a precisely balanced loan to replace the remaining financing.
- Variable Stability: The structure allowed for capital repayment at any time—without the early repayment penalties common in standard business.
- Security Concept: The loan was backed by liquid funds held in separate, market-rate fixed-term deposit accounts.
- Efficiency: Parallel to project progress and the reduction of credit utilization, the cash collateral was gradually reduced and returned to the client.
The Result: Liquidity in Motion
By implementing this dynamic security structure, we transformed a rigid financing architecture into a "breathing" model.
Find further fronting examples from our practice here
Our Philosophy: Innovation and Generational Thinking
Fronting at Westend Bank is an expression of our Beyond Banking approach, offering Family Offices and investors innovative financing solutions and access to new financial horizons.
We see ourselves as partners to clients and Family Offices whose time horizons are measured not in quarters, but in generations. Our structures are designed to possess the necessary resilience to guarantee permanence while offering the agility to seize the opportunities of the future. The Foundation for Your Vision True value is created in discreet dialogue at eye level. We invite you to design the structural framework for your next vision together with us.
The Foundation for Your Vision
True value emerges through discreet dialogue at eye level. We invite you to shape the foundations for your next vision together with us.
Contact us now